By Jeff Dunsavage, Head of Research Publications and Insights, Triple-I
One hundred years ago, on September 18, 1926, a Category 4 hurricane struck Miami, causing economic losses of about $105 million in 1926 dollars. Based on estimated insurance penetration of 15.7%, the insured losses amounted to approximately $16.5 million, according to a Swiss Re Institute analysis.
Swiss Re projects that a repeat of the 1926 Great Miami Hurricane could cause around $200 billion in insured losses today and that a Category 5 hurricane making landfall in Miami or Tampa Bay could generate insured losses of $300 billion or more, which would be larger than any recorded single-event insured loss to date.
“One hundred years after the Great Miami Hurricane, the question is not simply how powerful the next major hurricane will be, but what it will encounter when it reaches shore,” said Balz Grollimund, head of catastrophe perils at Swiss Re. “That lesson extends well beyond Florida: As populations and asset values increase in areas exposed to natural catastrophes, so does the potential for large insured losses.”
While the 2026 Atlantic hurricane season has been quiet so far, Grollimund cautioned, “It only takes one major storm making landfall in a highly exposed area to turn a quiet season into a costly one.”
For the insurance industry, the Great Miami Hurricane of 1926 was the country’s most devastating natural disaster since the 1906 San Francisco earthquake and fire and an early warning of how rapid urban development could create a major accumulation risk.
“When Miami was incorporated in 1896, only 30 years before the hurricane hit, it had just over 300 residents,” the report says. “By September 1926, Miami was a boomtown, with more than 100,000 residents in Dade County, including the City of Miami. Urban development – including homes, hotels, roads and other infrastructure – had expanded rapidly into previously undeveloped areas, making Miami one of the fastest-growing cities in the United States.”
One hundred years later, Swiss Re says, “More than two million homes in the Miami metropolitan area, with a combined reconstruction cost exceeding $600 billion, are now at moderate or greater risk of hurricane wind damage.”
Where a hurricane makes landfall is critical. Hurricane Andrew struck around 20 miles south of Miami as a Category 5 storm in 1992, largely sparing Miami’s much larger concentration of insured property. Swiss Re Institute estimates the same track today would cause close to $100 billion in insured losses, compared to the $300 billion loss that could be experienced by the same storm striking Miami or Tampa Bay.
A call to resilience
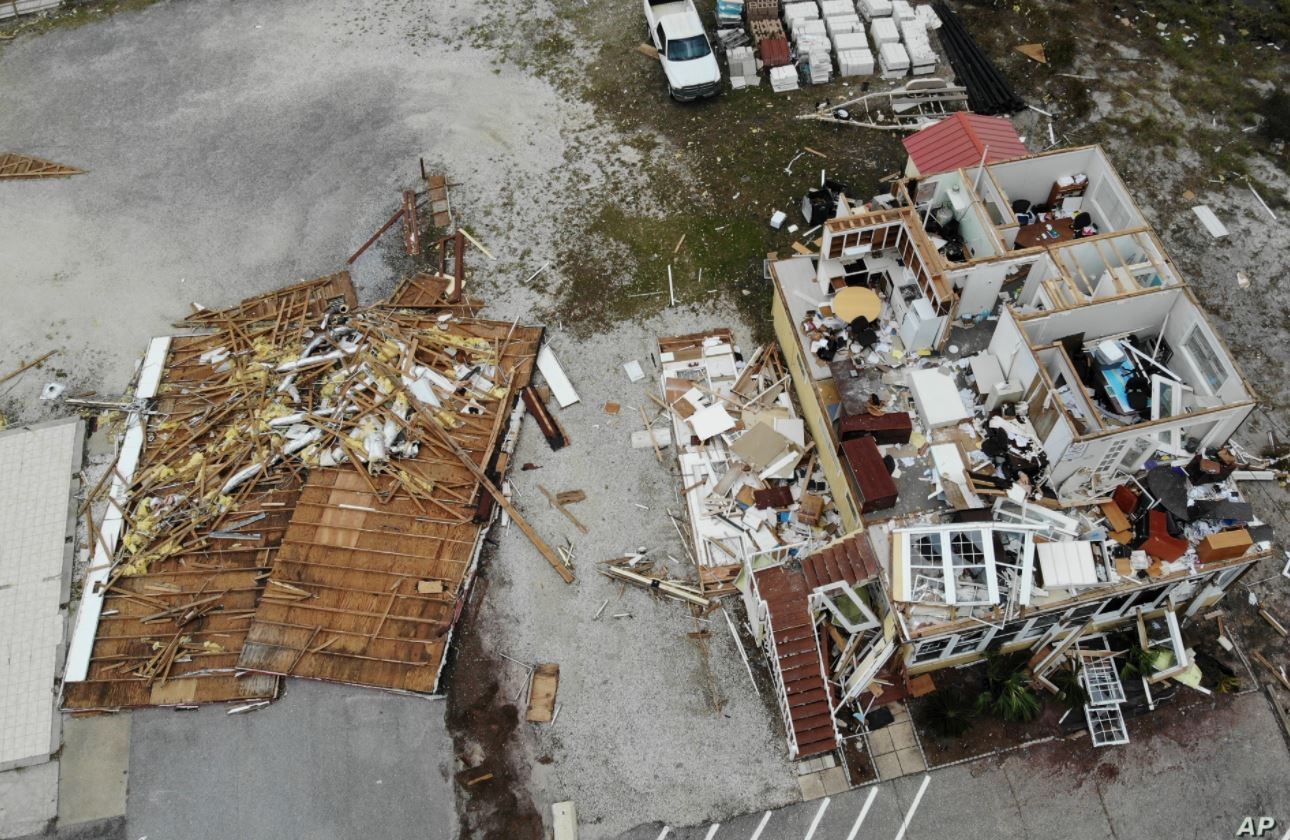
The centenary is a good time to reflect on the importance and power of resilience. Stronger building codes and wind-resistant construction can help reduce hurricane losses. Updated standards helped newer homes in Florida withstand Hurricane Ian in 2022, while storm-proofed roofs further reduced vulnerability.
In addition, traditional and alternative reinsurance capacity can be more effective when supported by catastrophe modelling, disciplined accumulation management, and effective mitigation.
“Florida’s growth has transformed the risk landscape, making it increasingly important for insurers, communities and policymakers to understand how exposure is changing,” said Monica Ningen, CEO for U.S. property and casualty reinsurance at Swiss Re. “Stronger building standards have improved resilience, but continued population and property growth in exposed areas means the potential for severe losses remains significant. Effective mitigation and risk modelling can help manage that risk, while reinsurance helps insurers absorb the volatility of severe events.”
Not just Florida and not just coastal
The lessons of the past century are not simply relevant to Florida or only to coastal areas. In recent years, inland flooding from tropical storms and hurricanes have caused increasing damage.
In 2025, Tropical Storm Chantal dumped up to 10 inches of heavy rainfall across multiple North Carolina counties where less than 1 percent of households were covered by flood insurance. Chantal contributed to $500 million in economic losses, according to Gallagher Re’s Natural Catastrophe and Climate Report: Q3 2025. Much of Globe-Miami, Ariz. – struck by torrential rain from Category 2 Hurricane Priscilla in the Pacific, mere weeks after flash flooding killed at least three people – was also unprotected, highlighting a growing flood protection gap in areas once considered low-risk.
This year, Hurricane Lala passed south of Hawaii’s Big Island on August 15 without making landfall, but it left widespread wind and flood damage across the Hawaiian Islands, prompting an extended recovery effort. The storm’s combination of perils within hours of each other makes it difficult to assign a single cause of loss, complicating claims. Notably, Lala also triggered a payout for a coral reef protection parametric policy written by Munich Re. While parametric is generally seen more as a supplement to than a replacement for traditional indemnity policies, this payout highlights the potential for parametric in helping to manage catastrophe risks. During the 2025 Atlantic hurricane season, Hurricane Melissa triggered a $150 million parametric policy payout for Jamaica. That policy was backed by a bond issued in 2024 by the World Bank through its International Bank for Reconstruction and Development and structured by Aon Securities and Swiss Re Capital Markets.
Learn More:
Hurricane Lala Triggers Coral Reef Parametric Policy
How Hurricane Lala Could Complicate Claims
Atlantic Forecast Remains “Well Below Average” As Peak Hurricane Season Nears
Triple-I Issues Brief: Hurricanes (Members only)